

Form 2553 for an LLC: How the S Corp
Election Works and When It Helps
Table of contents
-
- What Is Form 2553?
- How to Prepare and File Form 2553
- When Does an LLC File Form 2553?
- When Might an S Corporation Election Help?
- Reasonable Compensation Is a Central Part of the Decision
- What Happens After the S Corporation Election?
- Example: A Growing Home Healthcare Agency
- What Happens If Form 2553 Is Filed Late?
- Conclusion
- Frequently Asked Questions
- Related BFG Tax Resources
- Choose the Next Step for Your Business
What Is Form 2553?
How to Prepare and File Form 2553
- Ownership
- Shareholder eligibility
- Tax classification
- Effective date
- Owner compensation
- Payroll requirements
- State tax treatment
- Accounting setup
- Filing and administrative requirements
When Does an LLC File Form 2553?
When Might an S Corporation Election Help?
- Is the business consistently profitable?
- What compensation would be reasonable for the owner’s work?
- How much profit may remain after that compensation?
- Is the potential employment-tax benefit large enough to matter?
- Will the potential benefit exceed the additional payroll, accounting, tax, and administrative costs?
- Is the ownership eligible for S corporation treatment?
Reasonable Compensation Is a Central Part of the Decision
An owner who performs services for an S corporation generally cannot simply characterize all compensation as distributions. The IRS requires reasonable compensation for services performed by shareholder-employees before non-wage distributions are made.
- Training and experience
- Duties and responsibilities
- Time and effort
- Compensation paid to other employees
- Comparable compensation
- Compensation agreements
- The source of the company’s gross receipts
- Timing and manner of compensation
What Happens After the S Corporation Election?
- Establishing or updating payroll
- Paying reasonable compensation
- Maintaining appropriate accounting records
- Recording wages and distributions correctly
- Making payroll tax deposits
- Filing employment tax returns
- Preparing the S corporation income tax return
- Providing shareholders with the appropriate tax reporting
- Monitoring state requirements
The business should also keep personal and business transactions appropriately separated and maintain records that support payroll, distributions, expenses, loans, and equity.
BFG Tax’s Payroll Solutions, Accounting and Bookkeeping Solutions, and Business Tax Preparation Solutions can help coordinate owner wages, business records, and S corporation tax reporting.
Example: A Growing Home Healthcare Agency
What Happens If Form 2553 Is Filed Late?
Review the IRS Late Election Relief requirements before requesting relief. For an LLC seeking both S corporation status and a late corporate-classification election, the general relief procedure includes a three-year-and-75-day limit and requirements concerning reasonable cause, prompt corrective action, eligibility, and consistent tax reporting. Do not assume an exception for an existing corporation also applies to that LLC.
Conclusion
Frequently Asked Questions
What is Form 2553 used for?
Can an LLC file Form 2553?
Is there a revenue threshold for an S corporation election?
How long does an LLC have to file Form 2553?
Does an S corporation election change an LLC into a corporation under state law?
Does an S corporation owner have to receive a salary?
Can a late Form 2553 election be corrected?
Related BFG Tax Resources
Earlier-stage business?
Explore BFG Tax’s Business Formation and Tax Strategy Guide to understand the decisions beyond the filing.
Choose the Next Step for Your Business
Choose the Next Step for Your Business
BFG works with growing businesses whose structure, payroll, accounting, and tax decisions need to be coordinated. The right scope depends on the business's complexity and the support it needs.
If you are evaluating whether an S corporation election may make sense for your LLC, BFG Tax can review the business's profitability, owner compensation, payroll requirements, potential tax implications, and additional administrative costs.
Have a question before booking?
Contact BFG Tax or call 844-BFG-4TAX.
Table of contents
- What Is Form 2553?
- How to Prepare and File Form 2553
- When Does an LLC File Form 2553?
- When Might an S Corporation Election Help?
- Reasonable Compensation Is a Central Part of the Decision
- What Happens After the S Corporation Election?
- Example: A Growing Home Healthcare Agency
- What Happens If Form 2553 Is Filed Late?
- Conclusion
- Frequently Asked Questions
- Related BFG Tax Resources
- Choose the Next Step for Your Business
What Is Form 2553?
Form 2553, Election by a Small Business Corporation, is used by an eligible corporation or other eligible entity to elect S corporation treatment for federal tax purposes. An eligible LLC may use Form 2553 to make the election without first filing Form 8832 when the applicable requirements are met.
The form is not the document that creates an LLC.
An LLC is created under state law. Form 2553 is a federal tax election that can change how an eligible entity is treated for federal tax purposes.
That distinction is important when evaluating an S corporation election.
How to Prepare and File Form 2553
Start by checking whether the LLC and its owners qualify for S corporation treatment. Confirm the intended effective date and the applicable IRS filing deadline before completing the form.
The election requires the business to meet applicable eligibility requirements. The IRS states that an S corporation generally must be a domestic corporation or eligible domestic entity, have allowable shareholders, have no more than 100 shareholders, have only one class of stock, and not be an ineligible corporation.
Before completing the form, review the LLC’s operating agreement and ownership rights as well as its federal and state tax position. S corporation eligibility includes a one-class-of-stock rule, so rights to distributions and liquidation proceeds can matter.
The filing review should cover:
- Ownership
- Shareholder eligibility
- Tax classification
- Effective date
- Owner compensation
- Payroll requirements
- State tax treatment
- Accounting setup
- Filing and administrative requirements
Use the current IRS Form 2553 Instructions to prepare and submit the election:
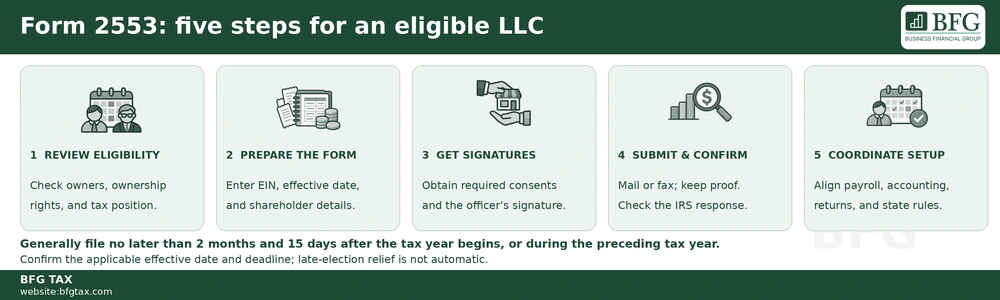
1. Enter the legal name, EIN, intended effective date, and required shareholder information.
2. Obtain the required shareholder consents and authorized officer’s signature. Check whether former owners must also consent.
3. Mail or fax the form to the IRS destination specified for the business’s location in the current instructions.
4. Keep a copy and proof of submission. Check the IRS notice for acceptance and the effective date; follow up as instructed if it does not arrive.
5. Coordinate payroll, accounting, Form 1120-S reporting, and state requirements with the effective date.
When Does an LLC File Form 2553?
Timing is an important part of an S corporation election.
For an election to take effect for a tax year, Form 2553 generally must be filed no later than 2 months and 15 days after the beginning of that tax year, or during the preceding tax year. The IRS provides rules for determining the applicable filing period and procedures for certain late elections.
The exact effective date and filing requirements can depend on the business’s circumstances.
Because a late or incorrect election can require additional procedures, an LLC considering S corporation treatment should review the effective date and filing deadline before submitting Form 2553.
When Might an S Corporation Election Help?
An S corporation election may be worth evaluating when a business has consistent profitability, and the owner is actively involved in generating income.
The potential benefit generally needs to be considered in relation to the owner’s compensation and the amount of profit that may remain after reasonable compensation.
Compare the potential employment-tax benefit on profit remaining after reasonable owner pay with the added payroll, accounting, tax preparation, and compliance costs. The reasonable-compensation factors are covered in the next section.
A useful review therefore asks:
- Is the business consistently profitable?
- What compensation would be reasonable for the owner’s work?
- How much profit may remain after that compensation?
- Is the potential employment-tax benefit large enough to matter?
- Will the potential benefit exceed the additional payroll, accounting, tax, and administrative costs?
- Is the ownership eligible for S corporation treatment?
There is no universal revenue or profit threshold at which an S corporation election automatically makes sense.
Reasonable Compensation Is a Central Part of the Decision
One of the most important considerations for an LLC considering S corporation treatment is owner compensation.
An owner who performs services for an S corporation generally cannot simply characterize all compensation as distributions. The IRS requires reasonable compensation for services performed by shareholder-employees before non-wage distributions are made.
Reasonable compensation is not determined by one universal percentage or formula.
Relevant factors can include:
- Training and experience
- Duties and responsibilities
- Time and effort
- Compensation paid to other employees
- Comparable compensation
- Compensation agreements
- The source of the company’s gross receipts
- Timing and manner of compensation
For a service business, this is especially important because the owner’s personal services may be a major source of the company’s revenue.
What Happens After the S Corporation Election?
The election is not the end of the process.
Once S corporation treatment applies, the business needs to operate and report consistently with that tax classification.
This may include:
- Establishing or updating payroll
- Paying reasonable compensation
- Maintaining appropriate accounting records
- Recording wages and distributions correctly
- Making payroll tax deposits
- Filing employment tax returns
- Preparing the S corporation income tax return
- Providing shareholders with the appropriate tax reporting
- Monitoring state requirements
The business should also keep personal and business transactions appropriately separated and maintain records that support payroll, distributions, expenses, loans, and equity.
BFG Tax’s Payroll Solutions, Accounting and Bookkeeping Solutions, and Business Tax Preparation Solutions can help coordinate owner wages, business records, and S corporation tax reporting.
Example: A Growing Home Healthcare Agency
Consider a hypothetical home healthcare agency formed as an LLC. Its owner now has consistent profit and is considering S corporation treatment. Before filing, the agency reviews the owner’s role and reasonable pay, verifies shareholder eligibility and its operating agreement, and chooses an effective date. It obtains the required consents, files Form 2553 by the applicable deadline, and confirms the IRS response. If accepted, it coordinates owner payroll, caregiver payroll, accounting, and the S corporation return. The example illustrates the sequence; it does not imply the election will save tax for every agency.
What Happens If Form 2553 Is Filed Late?
The IRS provides procedures for certain late S corporation elections when specific requirements are met, including reasonable cause and corrective action. Late-election relief is not automatic and depends on the applicable requirements.
A business that missed the election deadline should therefore not assume that the election is impossible or automatically effective.
The appropriate next step depends on the facts, filing history, intended effective date, and applicable IRS procedures.
Review the IRS Late Election Relief requirements before requesting relief. For an LLC seeking both S corporation status and a late corporate-classification election, the general relief procedure includes a three-year-and-75-day limit and requirements concerning reasonable cause, prompt corrective action, eligibility, and consistent tax reporting. Do not assume an exception for an existing corporation also applies to that LLC.
Conclusion
Form 2553 changes an eligible LLC’s federal tax treatment; it does not form the LLC or establish whether the election is financially worthwhile. Eligibility, reasonable owner compensation, the intended effective date, and filing requirements should be reviewed together.
Before filing, compare the potential benefit with the added costs and prepare payroll, accounting, and tax reporting to support the election. Keep proof of submission, confirm the IRS response, and seek qualified help if the election is late or the ownership arrangements raise eligibility questions.
Frequently Asked Questions
What is Form 2553 used for?
Can an LLC file Form 2553?
Is there a revenue threshold for an S corporation election?
How long does an LLC have to file Form 2553?
Does an S corporation election change an LLC into a corporation under state law?
Does an S corporation owner have to receive a salary?
Can a late Form 2553 election be corrected?
Related BFG Tax Resources
Explore these resources for coordinating structure, tax planning, and financial operations:
Earlier-stage business?
Explore BFG Tax’s Business Formation and Tax Strategy Guide to understand the decisions beyond the filing.
Choose the Next Step for Your Business
Choose the Next Step for Your Business
BFG works with growing businesses whose structure, payroll, accounting, and tax decisions need to be coordinated. The right scope depends on the business's complexity and the support it needs.
If you are evaluating whether an S corporation election may make sense for your LLC, BFG Tax can review the business's profitability, owner compensation, payroll requirements, potential tax implications, and additional administrative costs.
Have a question before booking?
Contact BFG Tax or call 844-BFG-4TAX.
Related BFG Tax Resources
This article provides general educational information and does not constitute tax, legal, payroll, accounting, or financial advice. S corporation eligibility, election deadlines, tax treatment, reasonable compensation, and state requirements depend on the business’s circumstances and applicable laws. Consult qualified tax and legal professionals before making an S corporation election.